What is the market overview and scope of the Processed Nonferrous Metal Market?
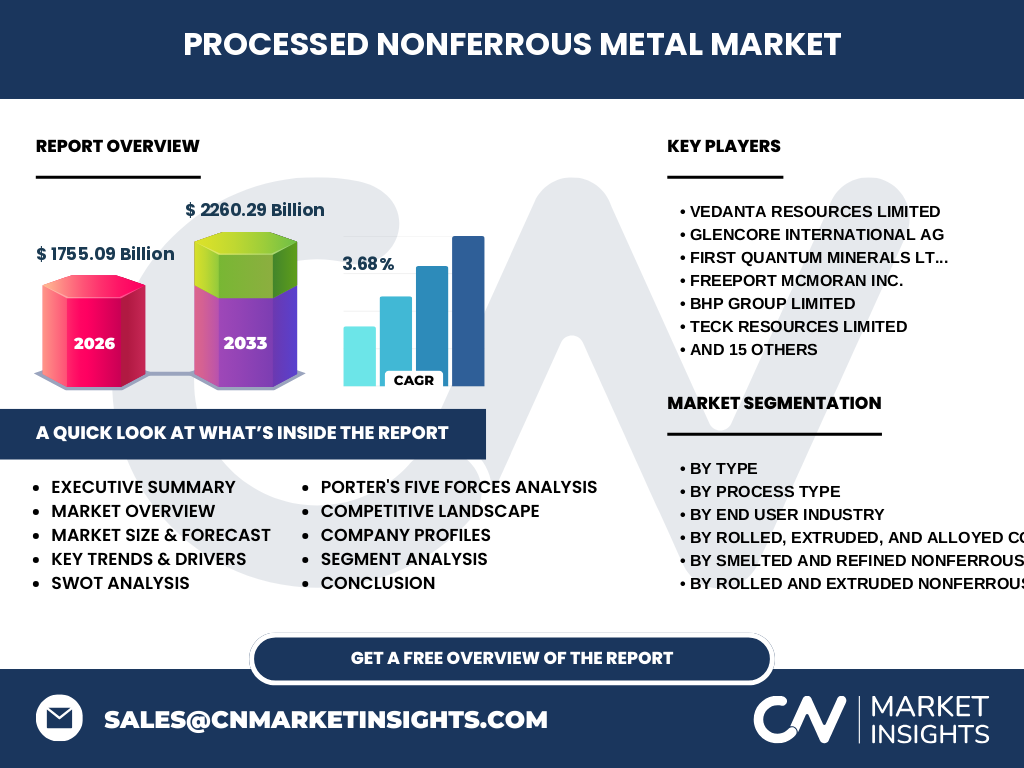
Our analysis indicates the Processed Nonferrous Metal Market represents a foundational pillar of global industrial manufacturing, encompassing the smelting, refining, rolling, and extruding of essential base metals excluding raw aluminum. The market size stands at 1755.09 Billion in 2026, driven by critical demand across automotive and electronic power sectors.
Key market drivers, restraints, challenges, and opportunities shaping Processed Nonferrous Metal Market
Growth is propelled by electric vehicle adoption and renewable energy grid expansions requiring extensive copper rods and nickel alloys. However, tightening environmental regulations by bodies like the EPA and localized energy cost volatility act as severe restraints. Opportunities abound in closed-loop recycling infrastructure for secondary metals.
Emerging trends and growth patterns in Processed Nonferrous Metal Market
The shift toward low-carbon smelting is redefining industry standards. Major producers are increasingly investing in green hydrogen and hydroelectric-powered refineries to reduce Scope 1 emissions, aligning with stringent European Union CBAM mandates that penalize carbon-heavy supply chains.
COVID-19 impact analysis on the Processed Nonferrous Metal Market
The pandemic caused severe supply chain fractures, port congestion, and temporary mine shutdowns across major Latin American and Asian extraction hubs. The subsequent recovery trajectory has been marked by aggressive fiscal stimulus directed at infrastructure, propelling demand back above pre-pandemic baselines.
Competitive landscape and strategic dynamics in the sector
The industry features a mix of consolidated mining giants and specialized refiners. Firms leverage vertical integration to secure raw ore supply while optimizing processing efficiency. Strategic mergers and joint ventures focus on securing critical transition minerals like nickel and copper to hedge against geopolitical trade disruptions.
Executive Summary: High-level synthesis of key findings
Valued at 1755.09 Billion in 2026, the market is poised to reach 2260.29 Billion by 2033, expanding at a steady 3.68% CAGR. Electrification and urban infrastructure expansion remain the primary catalysts dictating long-term capital allocation strategies.
Market Forecast: Projected Growth from 2027 to 2033
Based on our econometric models, the market will expand from its 2026 valuation to 2260.29 Billion by 2033, maintaining a compound annual growth rate of 3.68%. This expansion is sustained by continuous technological upgrades in rolling and extruding facilities worldwide.
Segmentation analysis of the Processed Nonferrous Metal Market
Segmentation spans type, process type, and end-user industry. Key type categories include Smelted And Refined Nonferrous Metal (Except Aluminum), Rolled, Extruded And Alloyed Copper, and Secondary Smelted Refined And Alloyed Nonferrous Metal. These cater directly to specialized applications in automotive and electronic power.
Regional market analysis and geographic distribution
Asia-Pacific dominates consumption due to massive manufacturing hubs in China and India, whereas Latin America and Africa control primary extraction and initial smelting. North America and Europe focus heavily on secondary smelting and high-precision rolling and extruding operations.
In-depth regional review of key operational zones
Asia-Pacific remains the undisputed epicentre for copper tubes and zinc sheet demand, supported by rapid urbanization. Meanwhile, European markets enforce stringent circular economy regulations, forcing regional processors to scale up secondary smelting capabilities for recycled lead and nickel.
Company profiles and strategic positioning of leading entities
Industry leaders like Glencore International AG, BHP Group Limited, and Rio Tinto dominate raw resource access, while specialized refiners such as Aurubis AG and Korea Zinc Co. Ltd. excel in high-purity copper and zinc production for advanced electronics.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate-to-high due to the scarcity of high-grade ore deposits. Threat of substitution is low given the unique thermal and electrical conductivity of nonferrous metals, while competitive rivalry is intense among established global players.
SWOT analysis of the global industry
Strengths include robust global distribution networks and essential product utility. Weaknesses involve high energy dependency. Opportunities lie in secondary metal recycling, while threats center on resource nationalism and shifting trade tariffs.
Value chain analysis from raw materials to end-users
The value chain flows from upstream mining and extraction through midstream smelting, refining, rolling, and extruding, culminating in downstream deployment within automotive wiring harnesses, construction panels, and electronic power grids.
Investment insights and high-potential areas
Investors should target greenfield recycling facilities and advanced alloying technologies. Companies with proprietary low-carbon refining techniques are best positioned to capture premium pricing under upcoming international carbon accounting frameworks.
Conclusion and key takeaways for stakeholders
The Processed Nonferrous Metal Market offers stable growth backed by a 3.68% CAGR through 2033. Success requires balancing stringent environmental compliance with agile supply chain management to capitalize on surging electrification trends.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining official trade registry data, primary stakeholder interviews with C-suite executives across top mining firms, and secondary macroeconomic indicators from organizations like the International Copper Study Group.
Scope of the report and analytical limitations
This report covers global production, consumption, trade flows, and pricing dynamics across specified nonferrous categories from 2026 to 2033. Limitations include unforeseen geopolitical embargoes and sudden regulatory shifts in primary export nations.
Recent developments, partnerships, and strategic moves
Recent strategic moves highlight joint ventures in deep-sea mineral exploration, long-term power purchase agreements utilizing renewable energy for smelting complexes, and increased capital expenditure toward closed-loop recycling plants by major industry participants.